

German Inbound Slots Are About to Get Scarcer — Here’s What the July Capacity Data Shows


FBA Prep Germany
We streamline your German Amazon operations by handling FBA prep, managing removal orders, and forwarding shipments to any German Fulfillment Center for FBA and Vendor accounts.
Every August, sellers assume there will be a truck available in October. That assumption is getting riskier. The July Logistics Managers’ Index data points to transportation capacity shrinking faster than demand in both the US and EU markets, and Germany’s road freight network feeding Amazon FCs is one of the tightest links in that chain. If you run Amazon FBA Prep services in Europe through a German prep partner, this is not a background trend to read about later—it is a booking decision you need to make in the next few weeks.
This piece breaks down what the July capacity data actually shows, why it hits German inbound slots specifically hard, and what you should confirm with your prep partner before assuming a truck will be there when you need it.
What the July Capacity Data Is Actually Showing
The Logistics Managers’ Index tracks how logistics professionals rate current and future conditions across inventory, warehousing, and transportation. The July reading points to a specific and uncomfortable pattern: transportation capacity is contracting at a faster pace than shipping demand is falling. In plain terms, carriers are pulling trucks and drivers out of the network faster than shippers are reducing what they need to move.
That is a different problem than a demand spike. A demand spike is temporary and self-correcting—rates go up, more capacity gets pulled back in, things settle. A supply-side contraction is stickier. Carriers exiting the market, consolidating routes, or shifting fleets to more profitable lanes does not reverse quickly just because Q4 volume arrives. It means the baseline amount of available road freight capacity going into peak season is already lower than it was a year ago.
For sellers relying on road freight capacity 2026 planning assumptions carried over from prior years, this is the part that gets missed. Last year’s booking lead time is not this year’s booking lead time. If you are still assuming a two-week window between requesting a slot and getting a truck, the data suggests that window is already narrower, and it will likely get narrower still as October and November volume ramps up across both US and EU lanes simultaneously.
Why This Hits German Inbound Slots Harder Than Most Routes
Germany is not just another EU market for Amazon inbound—it is the highest-volume FC network in the region, and it sits at the center of freight corridors that also serve France, Benelux, and parts of DACH. That concentration is normally an advantage. During a capacity squeeze, it becomes a bottleneck.
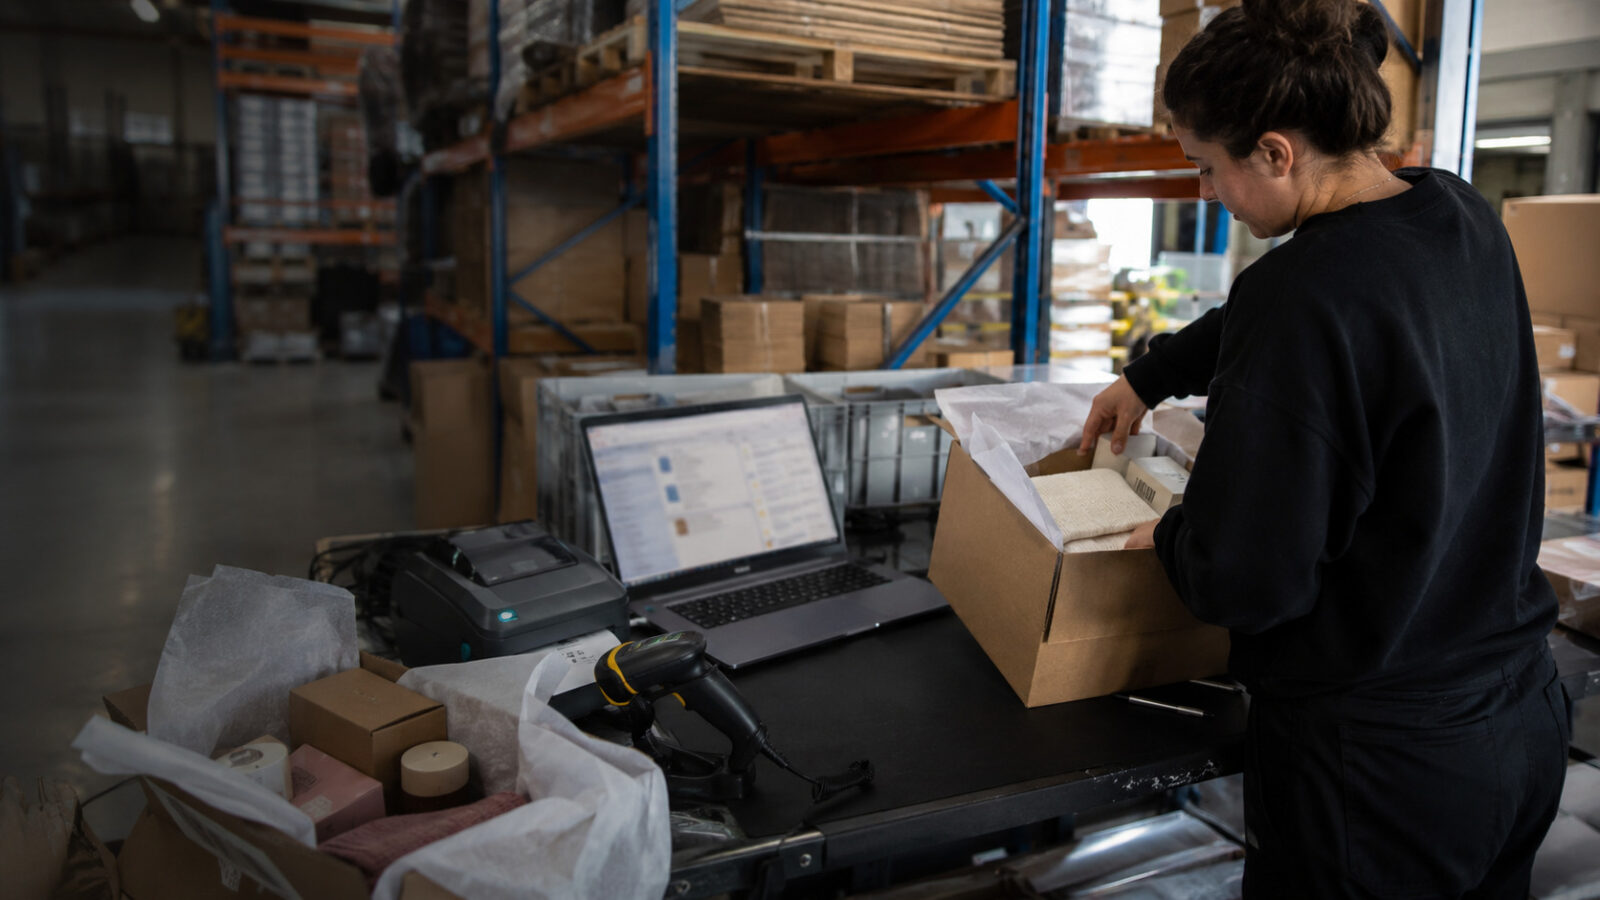
Here is the mechanism: German prep centres depend on road freight to move goods from ports, rail terminals, and river barges into the prep facility, and then again from the prep facility to the Amazon FC. Each of those legs competes for the same shrinking pool of trucks and drivers. When capacity tightens across the network, carriers naturally prioritize the highest-paying, most reliable, most recurring contracts first. Spot-booked or short-notice freight gets pushed to the back of the queue.
A seller who books inbound slot booking in Germany on short notice in October is not competing against other Amazon sellers directly—they are competing against every other shipper trying to secure the same trucks during the same tightening window. If your prep partner has not locked in carrier capacity commitments ahead of time, your shipment is the one that gets bumped when a contracted customer needs the same truck.
This is also where the German trucking capacity squeeze compounds with FC-side constraints. Amazon FCs in Germany already run tight appointment scheduling during peak. A carrier delay of even a day or two can push your FC appointment past its window, forcing a rebooking cycle that adds a week or more to your actual inbound timeline.
What to Book Now Instead of Waiting for Q4
The instinct to wait—get more sales data, confirm final SKU counts, see how September looks—is understandable but expensive in this environment. Waiting assumes slots will still be there closer to Q4. The July LMI data Germany reading suggests the opposite: capacity is tightening now, before peak volume even arrives, which means the crunch during peak will be worse than in a normal year.
Three things are worth locking in now rather than in six weeks:
- Prep centre storage windows for your peak-season inventory, confirmed in writing with dates, not verbal estimates.
- Carrier capacity for the leg between your prep centre and the Amazon FC, ideally tied to a named carrier relationship rather than a general spot-market assumption.
- FC appointment slots booked as early as Amazon’s system allows, since appointment availability tightens in direct proportion to how close you get to peak weeks.
If you are working with a partner offering FBA prep services in Europe, ask directly whether they have already reserved carrier capacity for Q4 or whether they are planning to book it closer to the date. A partner who has pre-committed volume with carriers is in a materially different position than one relying on the spot market when things get tight. This is the single clearest signal of whether your inbound plan for Germany is resilient or exposed.

How This Compounds With the Current River-Freight Disruption
Road freight is not the only inbound channel feeling pressure. German inbound logistics also depends on river freight—barge movement along the Rhine and connecting waterways—for a meaningful share of container and bulk cargo reaching inland terminals near major prep hubs. Disruption on that side of the network does not stay contained to barges; it pushes displaced volume onto trucks.
When river freight capacity drops, shippers who normally move cargo by barge shift to road transport as the next available option. That additional volume lands on the same trucking network that is already contracting under the pattern shown in the July LMI data. The result is not two separate problems—it is one compounding problem where road freight absorbs both its own baseline demand and displaced river-freight demand at the same time capacity is shrinking.
For a seller assuming that road freight is a reliable backup if river freight is disrupted, this is the flawed assumption to correct now. Road is not a clean fallback when it is under the same pressure from a different direction. A German prep partner who understands this compounding effect will be actively diversifying carrier relationships and building buffer time into their inbound plan, not just quoting a standard lead time from a normal year.
Ask your prep partner specifically how river-freight disruption has affected their inbound volumes in recent weeks, and whether that displaced cargo has already started competing for the same road capacity your shipments depend on.
What to Confirm With Your German Prep Partner Before Peak
A conversation with your prep centre right now is worth more than a booking form filled out later. The goal is to understand whether their carrier relationships are structured to absorb a capacity squeeze or whether they are exposed to it in the same way an individual seller booking freight independently would be.
Specific questions worth asking directly: Do they have contracted carrier capacity for the storage-to-FC leg, or do they rely on spot-booked trucks during peak weeks? What buffer time do they build into their published lead times for German prep booking urgency periods like this one? How have recent river-freight disruptions already affected their inbound timelines, and has that changed their carrier sourcing strategy?
A partner who can answer these with specifics—named carriers, contracted volume commitments, buffer stock policies—is one you can plan Q4 around with reasonable confidence. A partner who answers vaguely, or who has not adjusted their approach despite the capacity data, is one where your inventory is exposed to the same squeeze everyone else is facing, just with an extra layer of uncertainty about whether they are managing it.
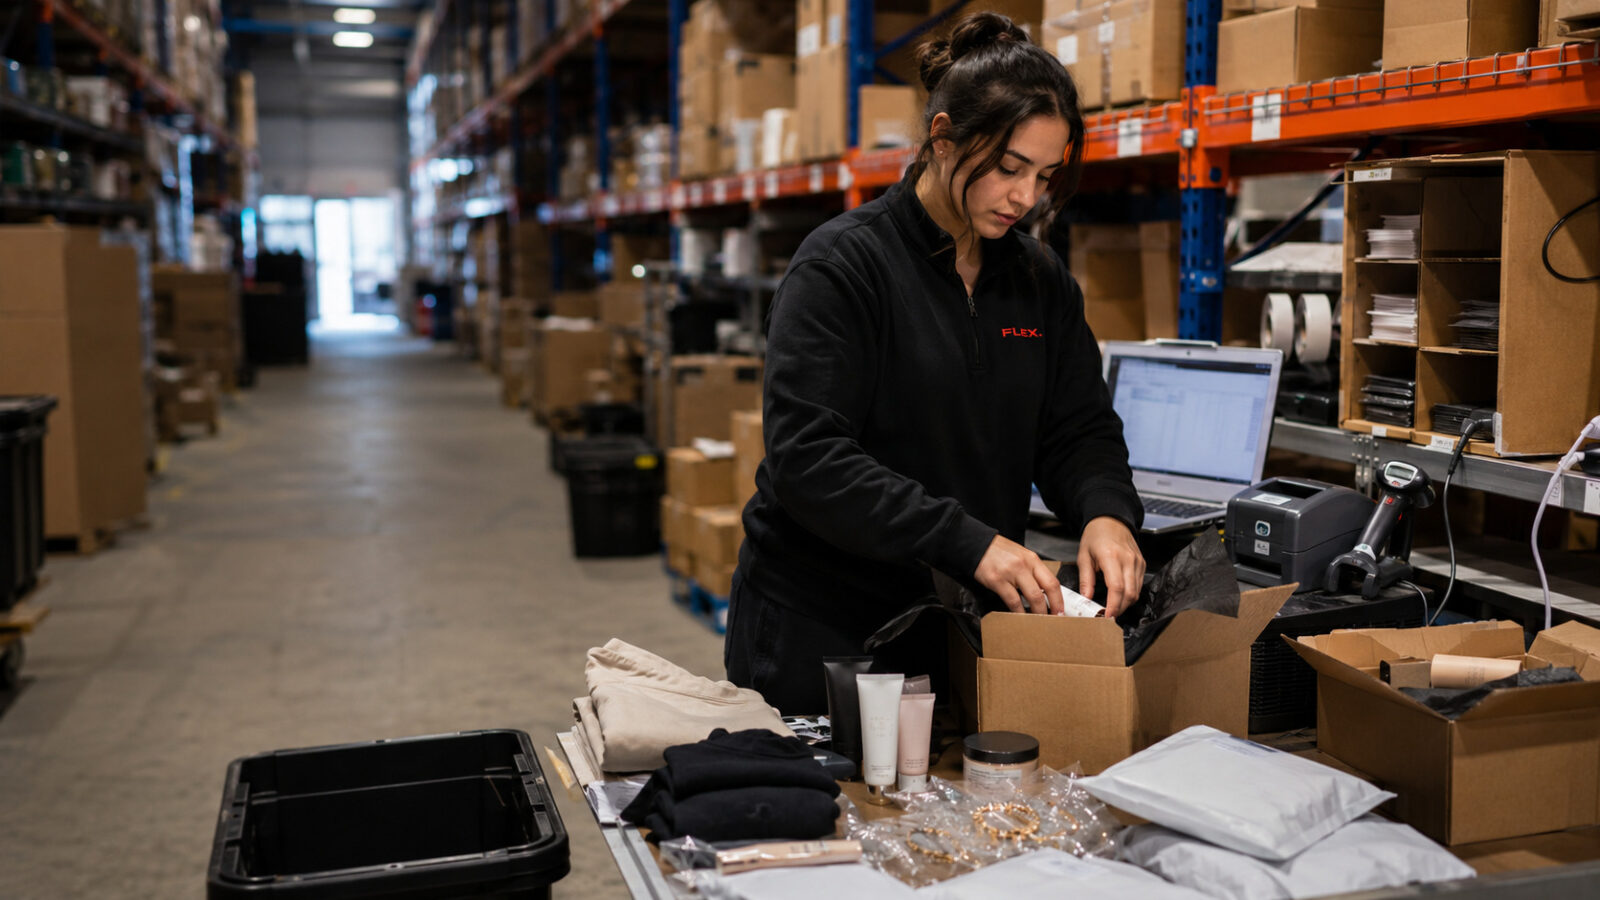
This is also the point to confirm your own carton compliance and pallet prep requirements are locked in, since any rework at the prep stage adds days you cannot afford to lose once carrier capacity is already tight. Treat this as a two-way audit: your prep readiness and their carrier readiness both need to hold.
Operational Control Points to Verify Now
- Confirmed carrier capacity commitment for the prep centre to Amazon FC leg, not a spot-market assumption.
- Written storage window dates at the prep centre covering your full peak-season inventory volume.
- FC appointment slots booked as early as Amazon’s system currently allows for your SKUs.
- Buffer time built into the inbound plan to absorb a one to two day carrier delay without missing the FC window.
Common Mistakes to Avoid
- Assuming last year’s booking lead time still applies to this year’s tighter capacity market.
- Treating road freight as an automatic backup when river-freight disruption is already displacing volume onto trucks.
- Booking prep and FC slots separately without confirming both legs align on timing.
- Waiting for confirmed Q4 sales forecasts before locking in storage and carrier capacity.
When to Escalate
- Escalate to your prep partner immediately if they cannot name a contracted carrier for peak-season inbound.
- Revisit your inbound plan if FC appointment availability has already shifted later than your original Q4 forecast assumed.
- Bring in a specialist partner if your current setup has no buffer stock policy for a multi-day carrier delay.
Treat This as a Booking Decision, Not a Watching Brief
The July capacity data does not tell you exactly how bad peak season will get. It tells you the direction is unfavorable, and that the gap between available trucks and required volume is already widening before the heaviest shipping months arrive. That is enough information to act on now rather than in October.
The practical decision in front of you is narrow: either your prep partner has already secured carrier capacity commitments for the storage-to-FC leg, or they have not. Either your FC appointment is booked, or it is sitting in a queue that gets longer every week. Either your inbound plan accounts for river-freight displacement pushing more volume onto an already tightening road network, or it assumes conditions that no longer hold.
None of this requires predicting the future precisely. It requires confirming, in writing, that the commitments underneath your Q4 inbound plan for Germany are real rather than assumed. A seller who books pre-Amazon storage and carrier capacity now is working from a position of buffer. A seller who waits until forecasts firm up is working from a position of hope, at exactly the point in the year when hope is the least reliable planning tool available.
If your current prep setup has not been stress-tested against this capacity picture, that conversation is worth having this week, not after the first missed FC appointment shows you where the gap actually is.
The July LMI data shows transportation capacity shrinking faster than demand across the US and EU, and Germany’s road freight network feeding Amazon FCs is exposed to that squeeze directly. River-freight disruption compounds the problem by pushing displaced volume onto the same trucks already becoming scarce. Sellers should confirm carrier capacity commitments, storage windows, and FC appointments now rather than assuming availability closer to Q4. The practical question to answer this week is simple: does your German prep partner have contracted capacity, or are they exposed to the spot market like everyone else.
Reach out to the FLEX. team today via our contact form for a no-obligation quote tailored to your product range and sales volume. A more profitable fulfillment strategy could be closer than you think.

